Digital banking has moved beyond offering websites and mobile applications. Modern financial services connect artificial intelligence, payment infrastructure, customer data, and digital interfaces across banking services to create smoother online journeys. In this environment, smart banking Kenya is becoming closely associated with intelligent services that can respond to customer behaviour, support faster transactions, strengthen security, and make financial interactions more relevant. The connection between these technologies matters because customers experience banking as one journey rather than as separate systems.
AI Creates More Responsive Banking Experiences
Artificial intelligence can help banks understand patterns across large volumes of customer and transaction data. When applied responsibly, AI can identify frequently used services, recognise unusual activity, support customer service, and help institutions deliver relevant information through digital channels. Intelligent systems can use available data to make experiences more contextual.
For example, an online banking platform may identify a customer’s usual transaction behaviour and provide useful prompts based on that context. AI-powered assistants can also answer routine questions, guide users through common processes, and route more complex requests to human employees. This can reduce friction while keeping human support available.
Payments Become Part of the Digital Journey
Payments are central to online banking because customers expect transactions to be quick, convenient, and dependable. Kenya’s financial ecosystem has developed strong digital payment adoption, with an estimated 91% mobile money penetration and 47.7 million active mobile money subscriptions. The country’s projected digital payments market is also listed at $14.54 billion by 2028.
Connecting payment systems with intelligent platforms can improve how transactions are initiated, monitored, and supported. AI can analyse transaction patterns to identify potential anomalies, while connected payment infrastructure can allow customers to move between accounts, wallets, merchants, and other financial services more smoothly. When these components work together, payment activity becomes part of a broader digital experience rather than an isolated function.
Personalisation Improves Customer Experience
Customer experience involves more than speed. Customers expect banking platforms to remember preferences, provide relevant information, reduce unnecessary steps, and deliver consistent interactions across channels. AI and data analytics help institutions understand how people use digital services and identify opportunities for improvement.
Personalisation can highlight frequently used features, offer relevant guidance, and provide timely notifications based on customer behaviour. Analytics can also reveal where users face difficulties during digital journeys, allowing banks to simplify interfaces and processes. However, personalisation must respect privacy, transparency, and customer control.
Since financial institutions manage sensitive information, intelligent services require secure data practices, responsible governance, and clear communication about how customer information is collected and used.
Security Must Connect With Convenience
A seamless banking experience cannot come at the expense of security. As digital transactions increase, banks need systems that can identify suspicious behaviour without creating unnecessary barriers for legitimate customers. AI can support fraud monitoring by analysing transaction patterns and identifying activity that may require additional verification.
Modern authentication can connect security with customer experience by adjusting verification requirements according to transaction context, device behaviour, and risk signals. This approach can strengthen protection while reducing friction during routine interactions.
The goal is not simply to add more security steps. Strong identity management, biometric technologies, transaction monitoring, and responsible data governance can work together to create trusted, convenient, and secure digital banking experiences for customers.
Cloud and Data Infrastructure Enable Connected Services
AI, payments, and customer experience rely on dependable digital infrastructure. Banks need systems that process information quickly, support online channels, and scale with growing transaction volumes. Cloud technologies can provide flexible infrastructure for applications, data services, and digital banking operations.
Data quality is equally important because intelligent services depend on accurate and accessible information. When information remains separated across disconnected systems, creating consistent customer journeys becomes difficult. Better integration can connect transactions, customer interactions, service requests, and risk signals.
Banks can therefore focus on secure interoperability, suitable APIs, strong data governance, and flexible architectures that allow systems to exchange information efficiently without requiring every banking function to operate on one platform.
Building Omnichannel Customer Journeys
Customers increasingly switch between mobile apps, messaging platforms, branches, contact centres, and payment services. A connected banking strategy helps create consistent experiences across these channels. When customers begin a request online, relevant information should remain available when they continue through another channel, reducing repetition and unnecessary delays.
AI can support this connection by analysing interaction histories, identifying customer needs, and enabling intelligent routing. Integrated payment systems can also connect transactions across channels, while analytics help financial institutions understand where customers experience difficulties. Ultimately, effective digital banking depends on how well different technologies, channels, and services work together to deliver convenient, seamless, and consistent customer journeys.
The Role of Events in Financial Innovation
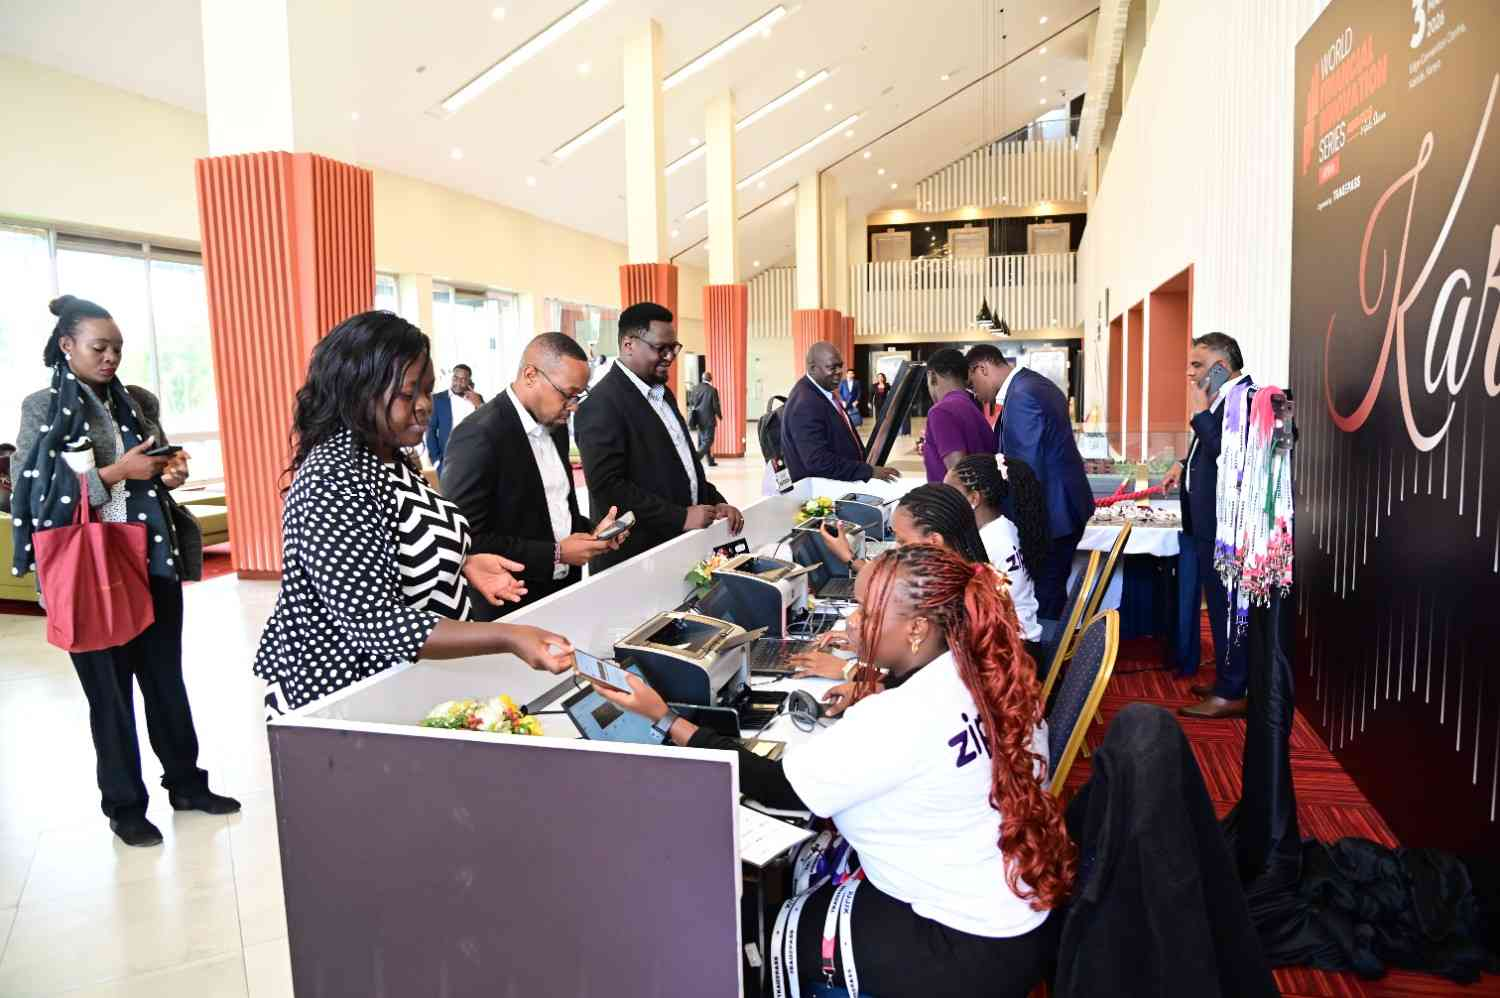
Industry discussions can help financial institutions understand how AI, payment technologies, security, cloud systems, and customer experience strategies are evolving. An East Kenya banking exhibition can provide a setting where professionals explore technology solutions, hear expert perspectives, and discuss practical approaches to digital transformation.
The conference discussions will cover AI-powered hyper-personalised customer experience, generative AI and data analytics, identity and security, AI for financial crime prevention, cloud scalability, and digital transformation. These themes demonstrate how modern banking increasingly requires collaboration across technology and business functions.
Conclusion
Smart banking is ultimately about connecting technologies into one coherent customer journey. AI can support personalisation and risk management, payment systems can enable convenient transactions, and integrated data and cloud infrastructure can connect services across digital channels. When these elements are designed around customer needs, financial institutions can create online experiences that are more responsive, secure, and consistent. This connected approach gives smart banking in Kenya a practical role in the continuing evolution of digital financial services.
For professionals exploring digital transformation and financial innovation, the World Financial Innovation Series (WFIS) Kenya brings banking, fintech, insurance, microfinance, technology, and financial services leaders together through conferences, exhibitions, networking, awards, and gala programmes. They support knowledge sharing, expert discussions, solution showcases, and business connections focused on AI, digital payments, customer experience, cybersecurity, cloud, data analytics, and emerging financial technologies across Kenya.